HOME EQUITY & DEBT CONSOLIDATION
Credit Card Debt Is Expensive.
Your Home Equity May Offer Another Option.
With credit card interest rates averaging over 22% on accounts assessed interest, many homeowners are exploring alternatives. If you've built equity in your home, you may have financing options worth considering - without necessarily refinancing your existing first mortgage.
$1.26T
Credit card debt (Fed NY Q2 2026)
22.36%
Average credit card interest rate on assessed-interest accounts (Aug 2026)
Serving homeowners across Texas & Arizona.
CONSOLIDATE DEBT
Understanding Home Equity Options
For homeowners across Texas and Arizona carrying high-interest revolving balances, home equity can serve as an educational alternative worth exploring. A Home Equity Loan provides a lump-sum disbursement with a fixed repayment timeline, whereas a Home Equity Line of Credit (HELOC) provides a revolving credit line you can draw on as needed. Both structures allow eligible homeowners to replace high-rate credit card debt with a structured, equity-backed financing vehicle.
- May offer lower interest rates compared to average high-interest credit cards
- Can simplify multiple monthly card obligations into a single predictable payment
- May provide structured repayment terms with stable fixed interest alternatives
- Can help optimize household monthly cash flow when managed prudently
Important Disclosure: Home equity loans and HELOCs are secured by your home. Costs and fees may apply. If payments aren’t made, your home could be at risk of foreclosure.
PRESERVE YOUR FINANCING
Love Your Mortgage Rate?
You May Be Able to Keep It.
Many homeowners locked in historically favorable primary mortgage rates that they are reluctant to give up. A home equity loan or Home Equity Line of Credit (HELOC) generally allows you to access accumulated home equity through a secondary lien, leaving your existing primary mortgage structure untouched.
- Existing Terms Remain Intact: Your initial first mortgage rate, payment schedule, and amortization continue exactly as they are.
- Independent Second Lien: Equity is accessed as a standalone financing instrument secured separately behind your first mortgage.
- Structured or Flexible Access: Choose between structured lump-sum disbursements or flexible revolving lines depending on your financial strategy.
*Educational overview only. Not an offer of credit, pre-approval, or commitment to lend. All financing options require formal application, property evaluation, and underwriting review.
ALTERNATIVE EQUITY APPLICATIONS
Beyond Consolidation:
Your Equity At Work
Explore strategic, non-debt methods homeowners leverage to utilize accumulated home equity toward long-term lifestyle enhancement and fiscal preservation.
Home Improvements & Renovations
Reinvest in your primary asset through targeted remodeling, energy-efficient upgrades, or square-footage expansion that may support your home's enduring appraised valuation.
Major Planned Expenses
Fund pivotal lifetime commitments such as specialized higher education tuition, elective medical procedures, or family milestones without liquidating invested retirement vehicles.
Emergency Reserves & Buffer
Establish a dormant liquidity reservoir to insulate household cash flow against unforeseen disruption, seasonal revenue dips, or unexpected emergency contingencies.
Financial Planning & Structure
Assess holistic capital structuring by balancing variable obligations, smoothing cash flow cycles, and aligning financing terms with long-term wealth preservation plans.
This information is educational and not financial advice. Options vary by borrower and property.
SIDE-BY-SIDE EVALUATION
Compare Your Equity Options
Review how the three primary equity vehicles function across funding, rate design, and first mortgage impact.
Home Equity Loan
FIXED SECOND MORTGAGE
- Funds: Single lump-sum payout delivered at closing
- Rate Structure: Fixed interest rate for the entire loan life
- Best For: Defined one-time costs and predictable project budgets
- 1st Mortgage Impact: Does not replace your existing first lien
- Payment: Fully amortized, consistent monthly installments
HELOC
REVOLVING CREDIT LINE
- Funds: Flexible credit line accessed on-demand as needed
- Rate Structure: Variable rate tied to index benchmarks
- Best For: Phased renovations, ongoing needs, or emergency reserves
- 1st Mortgage Impact: Does not replace your existing first lien
- Payment: Interest-only during draw; principal plus interest in repayment
Cash-Out Refinancing
NEW PRIMARY MORTGAGE
- Funds: Lump-sum difference between new loan and previous balance
- Rate Structure: Single new primary fixed or adjustable rate
- Best For: Combining debt when current mortgage rates align favorably
- 1st Mortgage Impact: Completely pays off and replaces your current first mortgage
- Payment: One single new consolidated monthly primary mortgage payment
Which option fits best depends on your goals, equity, credit profile, and property details.
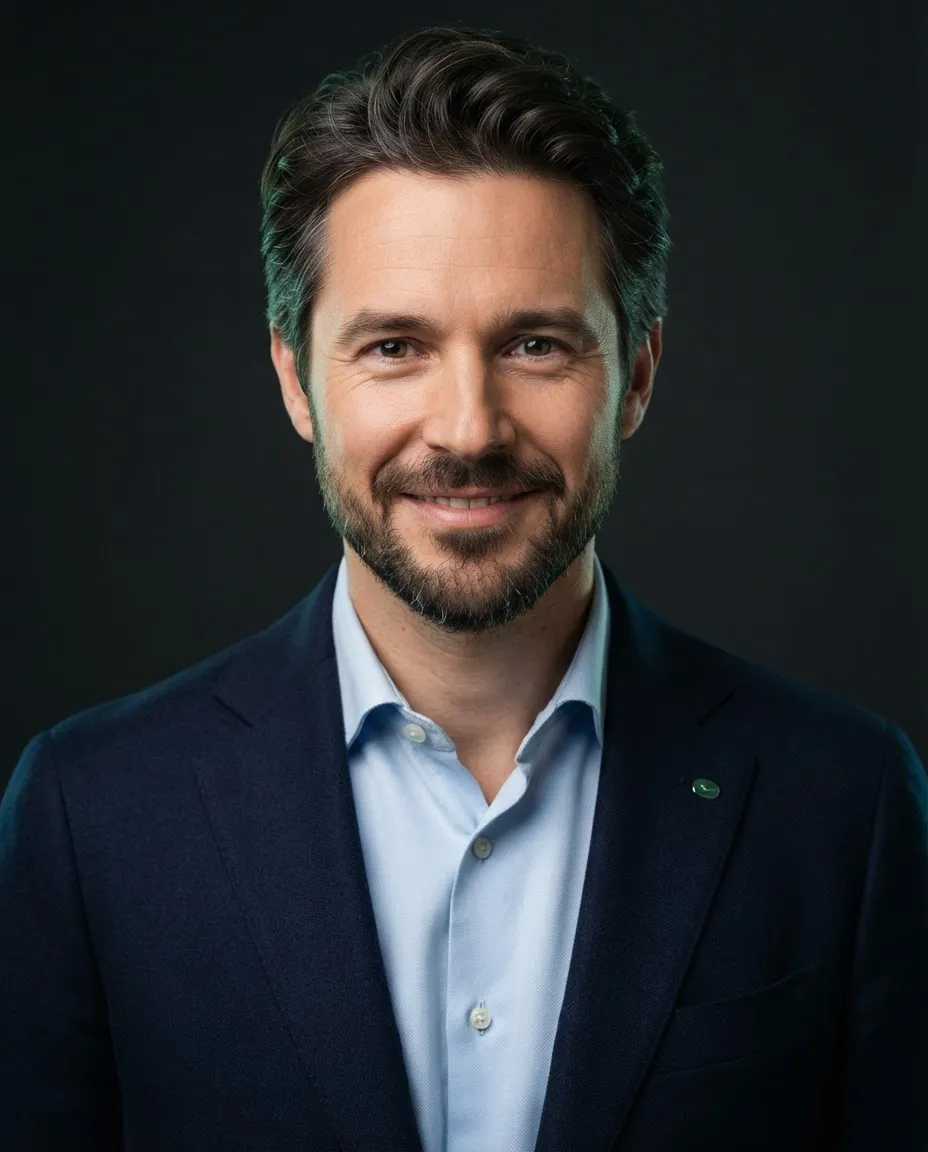
Jack Anderson • Mortgage Loan Officer | NEXA Mortgage LLC
ARTFULLY CRAFTED FINANCING
Meet Jack Anderson
Securing the right mortgage is not just about interest rates; it is about architecting a sustainable long-term financial framework. Jack Anderson brings an education-first philosophy and transparent lending guidance to every client relationship at NEXA Mortgage LLC, ensuring you make informed, confident decisions for your household.
Personalized Financing Options
Tailored mortgage structures aligned precisely with your immediate budget and future equity aspirations.
Transparent Guidance
Direct communication and clear line-by-line disclosures with zero hidden fees, ambiguous conditions, or surprises.
Education-First Approach
In-depth evaluations of trade-offs and scenarios so you understand every strategic facet before committing.
All financing subject to qualification. No guaranteed approvals.
Serving Texas & Arizona homeowners.
Explore Your Home Equity
Options
Answer a few quick questions to see which home equity paths may fit your goals.
Home equity financing is secured by your home and involves costs. If payments aren’t made, foreclosure risk may apply.
© Copyright 2023 . All rights reserved
.
. - |
.
Notice To Texas Loan Applicants: Consumers wishing to file a complaint against a mortgage banker, or a licensed mortgage banker residential mortgage loan originator, should complete and send a complaint form to the Texas Department of Savings and Mortgage Lending, 2601 North Lamar, Suite 201, Austin, TX 78705. Complaint forms and instructions may be obtained from the department’s website at www.sml.texas.gov
.
A toll-free consumer hotline is available at 1-877-276-5550. The department maintains a recovery fund to make payments of certain actual out of pocket damages sustained by borrowers caused by acts of licensed mortgage banker residential mortgage loan originators. A written application for reimbursement from the recovery fund must be filed with and investigated by the department prior to the payment of a claim. For more information about the recovery fund, please consult the department’s website at www.sml.texas.gov